The resident home buying guide.
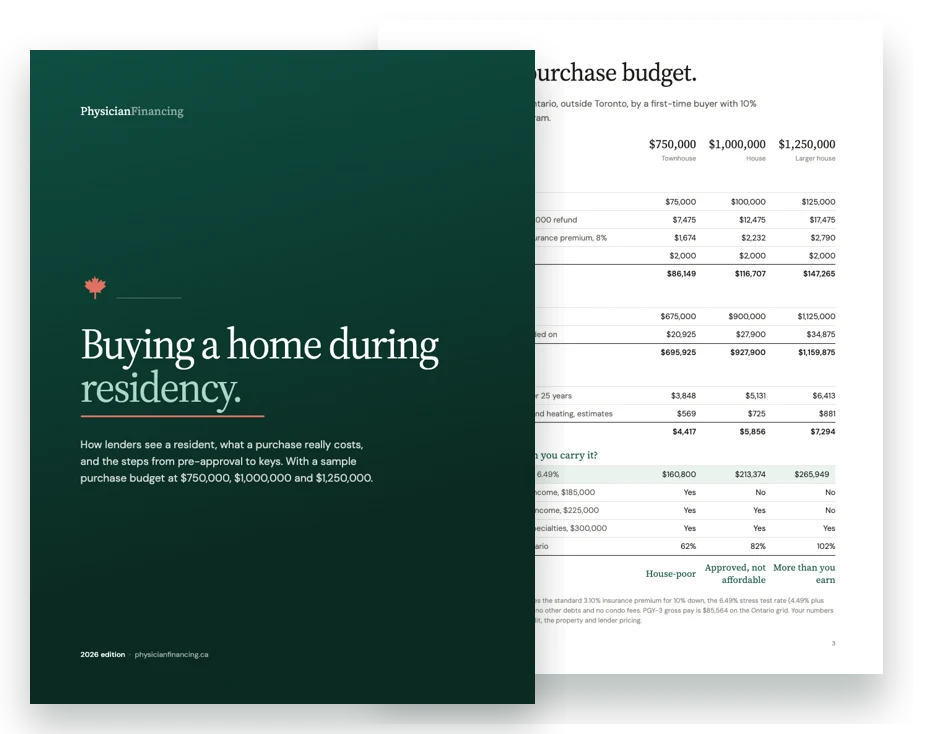
A sample purchase budget at $750,000, $1,000,000 and $1,250,000
How buying works, step by step
Closing costs and first-time buyer relief
What you need to apply, as a checklist
What happens if you move for fellowship
Physician programs qualify residents on the income they will earn as staff, not the resident salary.
A physician program could add
$0
to the home you can buy.
Estimate at 4.49%, stress tested at 6.49%, with 10% down, below the $1.5M insured limit.
If you cover the monthly interest by drawing on the line, that interest joins the balance, and next month you pay interest on it too. Put in your own numbers to see what it costs by the time you finish training.
Read the line of credit guidePaying it from the line costs $1,721 more over 3 years.
It depends on how long you will stay in the city and how much room your resident pay leaves each month.
Can I buy a home during residency?
Yes. Physician programs at some Canadian lenders qualify residents on projected income instead of the resident salary: $185,000 for PGY-1 and PGY-2, $225,000 for PGY-3 and later, and $225,000 to $379,000 by specialty in your final year or within 36 months of finishing.
See the full schedule and specialty chartDoes my line of credit count against me?
Yes, even in deferral or interest-only. Lenders count the balance as a monthly payment at the 5.25% minimum qualifying rate over 15 years. At $225,000 projected income, $100,000 owing ($801 a month) does not lower what you can buy, $200,000 ($1,602 a month) costs about $97,000 of buying power, and $250,000 ($2,002 a month) about $156,000.
Read the line of credit guideHow much down payment does a resident need?
At least 10% on a physician program, with at least 5% from your own money. The rest can be a family gift or borrowed funds such as your line of credit. With 20% down, at least 10% must be your own money.
Read the full guideCan I use the RRSP Home Buyers' Plan or an FHSA?
Yes, for a first home. You can withdraw up to $60,000 from your RRSP under the Home Buyers’ Plan and repay it over 15 years, and up to $40,000 from a First Home Savings Account.
What closing costs should a resident budget for?
Plan for 1.5% to 4% of the purchase price on top of the down payment, for land transfer tax where it applies, legal fees, a home inspection and moving. First-time buyers get relief in some provinces: Ontario refunds up to $4,000 of land transfer tax, Toronto up to $4,475 more, and BC exempts homes up to $500,000.
What do I need to apply?
A letter from your program confirming your specialty and year of training, your provincial college registration such as the CPSO in Ontario, proof of your down payment and a gift letter for any gifted amount, and current balances on your student loans and line of credit. First-year residents whose college listing is not live before closing have an exception path.
What kind of home qualifies?
Physician programs are for a home you live in, one or two units. The usual debt ratio limits still apply, and each lender sets its own rules on which stages of training it accepts.
Read the full guideWhat happens to my mortgage if I move for fellowship?
You can often port the mortgage to a new home, sell and pay the penalty, or ask your lender about renting the home out. The penalty to break a mortgage is usually the higher of three months’ interest or the interest rate differential. At renewal, lenders look at the income you actually earn.
Read the full guide


