Your corporation is a borrowing asset. Most banks don’t see it.
We set up your mortgage around your corporation, so you borrow on your real income and pay as little interest as possible.
3 waysLenders can read a corporation
50% to 80%More mortgage on a full corporate read
2 yearsOf statements lenders usually want
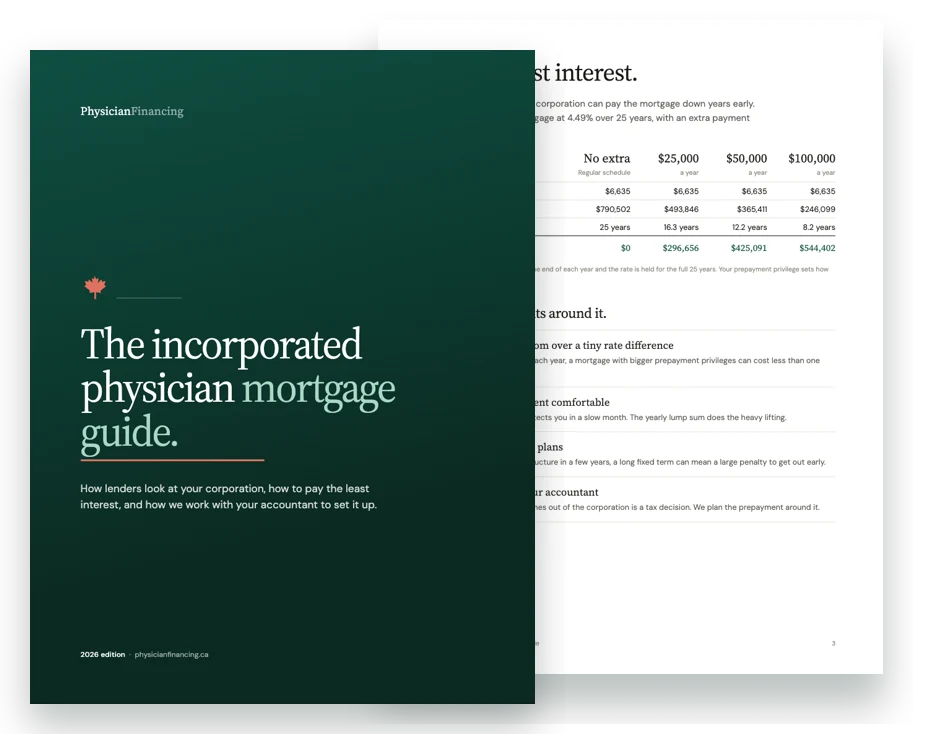
Use your corporation to pay it off faster.
You would save
$0
in interest, and be mortgage-free 12.8 years sooner.
Interest on the regular schedule25 years$0
Interest with the yearly extra12.2 years$0
Regular payment of $6,635 a month over 25 years. Your prepayment privilege sets how much you can add each year, and your accountant can tell you the best way to draw it from the corporation.
Your accountant sets your pay to save tax. We need those same numbers to get you the best mortgage, and the two plans pull in different directions if nobody connects them.
With your permission we talk to your accountant directly. We plan the salary and dividend mix before you apply, collect the documents, and time the yearly prepayment with your tax year. You are not stuck in the middle.
One of three ways: your salary only, your salary plus the dividends you take out, or the whole corporation including the profit left in the company. Most banks start with salary only. The lenders that read the whole corporation often approve a mortgage 50% to 80% larger than salary alone.
Most lenders read only the salary on your personal T4 and miss income left inside the corporation. Lenders that read corporate revenue, dividends and retained earnings together see your real earnings, which often raises the mortgage you can get by 50% to 80%.
Yes, once it comes out to you as salary or dividends. A yearly lump sum within your prepayment privilege is one of the cheapest ways to cut interest. On a $1,200,000 mortgage at 4.49%, an extra $50,000 a year saves about $425,000 in interest and pays it off almost 13 years early. Your accountant can tell you the best way to draw it.
Usually a comfortable regular payment plus a yearly lump sum. Pick a mortgage with enough prepayment room for what you plan to put down, even if the rate is a touch higher, and match the term to your plans, since breaking a fixed term early can mean a large penalty.
It depends on how your lender reads your income. If the lender reads salary only, a higher salary for a year or two before you apply can raise your approval. If the lender reads the whole corporation, it may not matter. Talk to us and your accountant one to two years before you plan to buy.
If you are a resident or fellow, or within 36 months of finishing training, a physician program can use projected income when your actual income is lower, as long as that income comes from medicine. After that, lenders usually want about two years of corporate statements.
Usually two years of corporate tax returns and financial statements, personal and corporate notices of assessment, your T4 and T5 slips, and your articles of incorporation. If you have a holding company, its details too. We can collect most of it straight from your accountant.
Yes, and we prefer to. Your accountant sets your pay to save tax and we need those same numbers for the mortgage. With your permission we talk to them directly, so the salary and dividend plan, the documents and the yearly prepayment all line up.
How do lenders look at my corporation?
One of three ways: your salary only, your salary plus the dividends you take out, or the whole corporation including the profit left in the company. Most banks start with salary only. The lenders that read the whole corporation often approve a mortgage 50% to 80% larger than salary alone.
I'm incorporated. Why does my bank think I earn less?
Most lenders read only the salary on your personal T4 and miss income left inside the corporation. Lenders that read corporate revenue, dividends and retained earnings together see your real earnings, which often raises the mortgage you can get by 50% to 80%.
Can I use money from my corporation to pay down my mortgage?
Yes, once it comes out to you as salary or dividends. A yearly lump sum within your prepayment privilege is one of the cheapest ways to cut interest. On a $1,200,000 mortgage at 4.49%, an extra $50,000 a year saves about $425,000 in interest and pays it off almost 13 years early. Your accountant can tell you the best way to draw it.
What payment structure costs the least?
Usually a comfortable regular payment plus a yearly lump sum. Pick a mortgage with enough prepayment room for what you plan to put down, even if the rate is a touch higher, and match the term to your plans, since breaking a fixed term early can mean a large penalty.
Should I raise my salary before I buy?
It depends on how your lender reads your income. If the lender reads salary only, a higher salary for a year or two before you apply can raise your approval. If the lender reads the whole corporation, it may not matter. Talk to us and your accountant one to two years before you plan to buy.
I just incorporated. Can I still qualify?
If you are a resident or fellow, or within 36 months of finishing training, a physician program can use projected income when your actual income is lower, as long as that income comes from medicine. After that, lenders usually want about two years of corporate statements.
What documents does an incorporated physician need?
Usually two years of corporate tax returns and financial statements, personal and corporate notices of assessment, your T4 and T5 slips, and your articles of incorporation. If you have a holding company, its details too. We can collect most of it straight from your accountant.
Do you work with my accountant?
Yes, and we prefer to. Your accountant sets your pay to save tax and we need those same numbers for the mortgage. With your permission we talk to them directly, so the salary and dividend plan, the documents and the yearly prepayment all line up.