All career stages

Growing a portfolio without killing your primary borrowing power.

Buy the first rental so it still leaves room for the next one. We plan the down payment, the lender and the structure before you make an offer.

20%Down on a rental you do not live in
Up to 100%Of duplex rent counted when you live there
5.25%The lowest rate any property is tested at

Does the rental carry itself?

Amortization

Each month the rental would cost you

$0

It breaks even at $4,198 a month in rent.

Rent coming in$0
Mortgage and costs going out$0

Mortgage payment of $3,298 a month on $640,000 borrowed. Other costs means property tax, condo fees, insurance, maintenance and an allowance for empty months. Before tax.

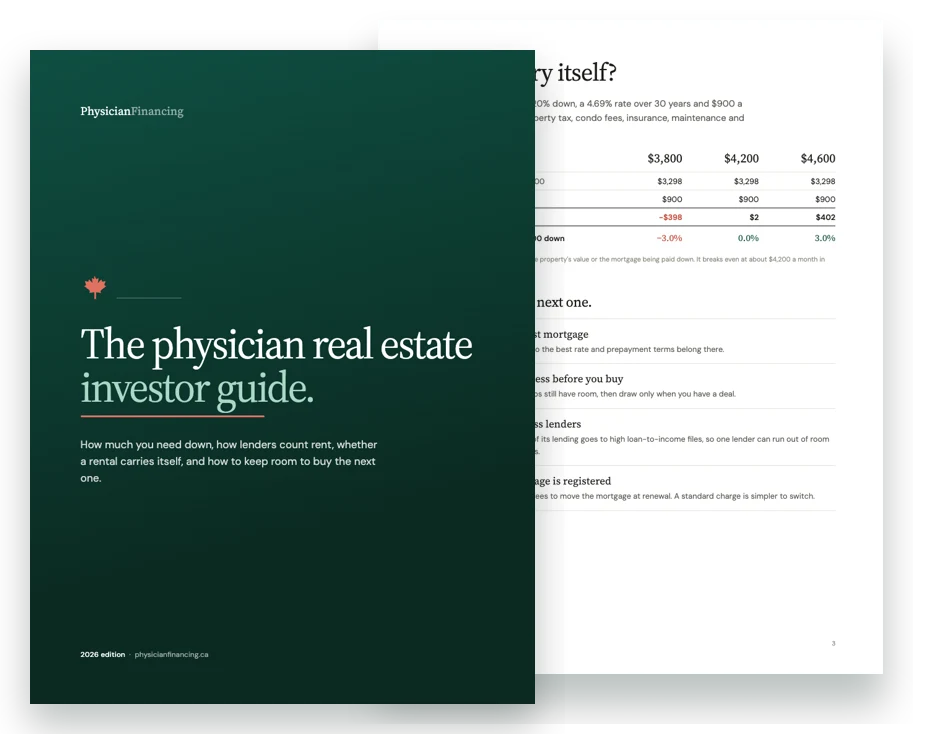
The physician real estate investor guide.

What you need down, by property type
How lenders count the rent
Cash flow on an $800,000 rental at three rents
How to keep room for the next property
BC and Ontario rules worth knowing
Download the guide PDF, 5 pages, free
The guide's cover and sample purchase budget page

How physician investors usually build it.

1. Give your home the best mortgageIt is usually your largest loan, so the best rate and prepayment terms belong there.
2. Set up access to your home equityArrange it while your ratios still have room, and draw only when you have a deal.
3. Buy the first rental with a different lenderSpreading lenders keeps any one lender from running out of room for you.
4. Keep each mortgage easy to moveA standard charge makes it simpler to shop every property at renewal.
5. Plan the next one before you need itEvery property is stress tested, so the order and timing of purchases matter.

If you sell and buy mid-term.

Port the mortgageMany mortgages can move to the new property with the same rate and terms, which can avoid a penalty. Your lender decides whether the new property and amount qualify, and there is usually a time limit.
Break it and start freshThe penalty is usually the higher of three months’ interest or the interest rate differential. That can make sense when today’s rates are well below yours, or you need a much larger mortgage.
Work out both before you listThe penalty, the porting rules and the new purchase price together decide which route costs less, so run the numbers before you sell.

Mistakes physician investors make.

Putting every property with one lenderConvenient until that lender reaches its own limits on your file and declines the next one.
Ignoring how the mortgage is registeredA collateral charge can mean fees to move each property at renewal, which weakens your hand when you shop.
Forgetting every property is stress testedEach purchase qualifies at the higher of your rate plus 2% or 5.25%, which eats into your room faster than the payment suggests.
Buying before arranging equity accessOnce the rental is on your file, your ratios are tighter, so access to your home equity is harder to set up afterwards.
Counting on rent you have not checkedUse real comparable rents and include empty months. A rental that only works at full occupancy is a stretch, not a plan.

Questions physician investors ask.

All guides

How much down payment do I need for a rental?

At least 20% on a property you will not live in. A single-unit rental cannot be insured, and a non-owner-occupied 2 to 4 unit can be insured at 20% down. If you live in one of the units, it is far less: 5% on the first $500,000 and 10% above for 1 or 2 units, and 10% for 3 or 4 units, on homes under $1.5 million.

How do lenders count rental income?

If you live in a duplex, insured lenders can count up to 100% of the rent from the other unit. In a 3 or 4 unit you live in, up to 50% of the rent, or the rent after expenses. For rentals you do not live in, lenders count part of the rent or the rent after expenses, and each lender has its own method. The lender you choose can decide whether the next property qualifies.

Do rental properties have to pass the stress test?

Yes. Uninsured mortgages qualify at the higher of your rate plus 2% or 5.25%, so each new property eats into your room faster than its payment suggests.

Read the full guide

Why do investors spread properties across lenders?

Since 2025, each federally regulated lender can only make so many uninsured mortgages above 4.5 times the borrower’s income, and rentals count. One lender can run out of room for you before the market does, so a plan across lenders keeps the next purchase possible.

How should I fund the down payment?

Many physician investors use equity in their home. Set up that access while your debt ratios still have room, and draw only when you have a deal. Borrowed money still counts as debt when you qualify for the rental.

Read the full guide

Does it matter how the mortgage is registered?

Yes, at renewal. A collateral charge can secure more than one loan with your lender and can mean fees to move the mortgage. A standard charge secures only the mortgage and is simpler to switch, which keeps you free to shop each property.

Read the full guide

What should I check before buying in BC or Ontario?

In BC, profit on a home sold within 730 days of buying it is taxed under the home flipping tax, which started January 1, 2025. In Ontario, a 25% tax applies to the whole price if any buyer is not a citizen or permanent resident, so a couple where one spouse is on a work permit should check first.

What does a rental need to carry itself?

Rent that covers the mortgage payment and every running cost: property tax, condo fees, insurance, maintenance and empty months. An $800,000 rental with 20% down at 4.69% over 30 years and $900 a month in costs breaks even at about $4,200 a month in rent.

More for physician investors.

Run the numbers before your next property.

See all physician tools
Jeff Mudrick
Emily Mudrick
Taylor Atkinson
Craig Austin
Talk to us
Jeff, Emily, Taylor and Craig
Mortgage agents and brokers
Ontario, BC and Alberta

Planning your next property?

Tell us what you own and what you want to buy next, and we'll plan the financing so each property leaves room for the next.

Jeff Mudrick, Lic. #M21001275Emily Mudrick, Lic. #M26000497BRX Mortgage Inc., Lic. #13463Taylor Atkinson, Licence #MB600364Craig Austin, Lic. #M19001164, Tango Ontario, FSRA #13691
I'm a:ResidentSole ProprietorIncorporatedInvestorRenewingMoving to Canada
Tools & Calculators