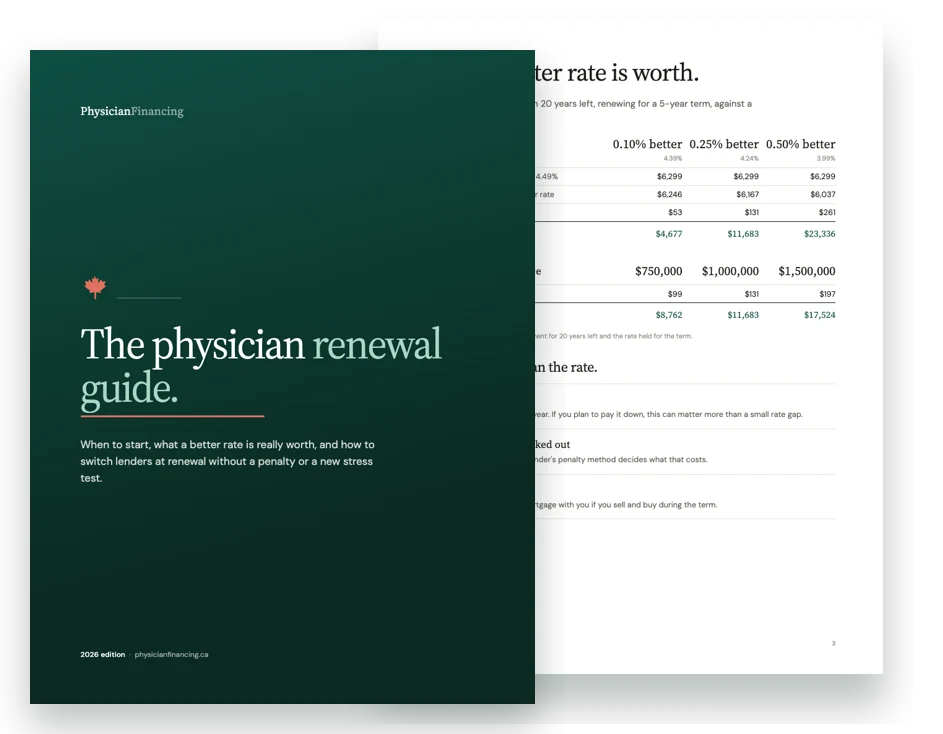
Your lender’s renewal offer is almost never their best number.
Compare before you sign. At the end of your term you can switch lenders with no prepayment penalty, and usually no new stress test.
44%Took their lender’s first offer (MPC, 2024)
21 daysMinimum notice before your term ends
No stress testOn a straight switch at renewal
Know when it’s worth switching.
We grade your mortgage against today’s physician rates, then keep watching. When rates move enough that switching early would save you real money, you hear from us.
18 months to renewal.
Today
What a better rate is worth.
Term
Over a 5-year term you would save
$0
in interest, and pay $131 less every month.
Interest at the lender’s offer4.49%$0
Interest at the better rate4.24%$0
Interest charged over the term, with the regular payment for the years left to pay it off. Switching at maturity carries no prepayment penalty.
About four months before your term ends. A new lender can usually hold a rate for 60 to 130 days, so you can lock one in early and still take a better rate if it appears. Your lender has to send the renewal statement at least 21 days before the term ends, which is too late to shop properly.
Yes. There is no prepayment penalty at the end of your term, so you can move to another lender then. Other switching costs, such as discharge, registration or appraisal fees, can still apply.
Usually not. Since November 21, 2024, an uninsured mortgage moving between federally regulated lenders at renewal skips the stress test if the balance and amortization stay the same, with up to $3,000 added for costs. Insured mortgages already did not have to requalify. Provincially regulated lenders, such as many credit unions, follow their own rules.
Only when the interest you save is bigger than the penalty. The penalty is usually the higher of three months’ interest or the interest rate differential, which can be large on a fixed rate. Track My Mortgage watches for the moment when switching early would save you real money.
A collateral charge can secure more than one loan with your lender and can be registered for more than the mortgage. To switch, everything it secures has to be repaid or moved, and there can be fees to remove and register it. A standard charge secures only the mortgage.
A switch moves the same balance and amortization to a new lender at the end of the term. A refinance borrows more or stretches the amortization, which is a new approval at the stress test rate.
Renewing with the same lender usually needs no new approval, and a straight switch keeps that advantage. If you refinance, you qualify on the income you actually earn now, so plan the timing.
Prepayment privileges, how the penalty is worked out if you break early, portability if you might sell and buy during the term, and whether the mortgage is registered as a standard or collateral charge.
When should I start looking at my renewal?
About four months before your term ends. A new lender can usually hold a rate for 60 to 130 days, so you can lock one in early and still take a better rate if it appears. Your lender has to send the renewal statement at least 21 days before the term ends, which is too late to shop properly.
Can I switch lenders at renewal without a penalty?
Yes. There is no prepayment penalty at the end of your term, so you can move to another lender then. Other switching costs, such as discharge, registration or appraisal fees, can still apply.
Do I have to pass the stress test again to switch?
Usually not. Since November 21, 2024, an uninsured mortgage moving between federally regulated lenders at renewal skips the stress test if the balance and amortization stay the same, with up to $3,000 added for costs. Insured mortgages already did not have to requalify. Provincially regulated lenders, such as many credit unions, follow their own rules.
Is it worth breaking my mortgage before renewal?
Only when the interest you save is bigger than the penalty. The penalty is usually the higher of three months’ interest or the interest rate differential, which can be large on a fixed rate. Track My Mortgage watches for the moment when switching early would save you real money.
What is a collateral charge, and why does it matter at renewal?
A collateral charge can secure more than one loan with your lender and can be registered for more than the mortgage. To switch, everything it secures has to be repaid or moved, and there can be fees to remove and register it. A standard charge secures only the mortgage.
What is the difference between a switch and a refinance?
A switch moves the same balance and amortization to a new lender at the end of the term. A refinance borrows more or stretches the amortization, which is a new approval at the stress test rate.
I bought on projected income. What happens at renewal?
Renewing with the same lender usually needs no new approval, and a straight switch keeps that advantage. If you refinance, you qualify on the income you actually earn now, so plan the timing.
Prepayment privileges, how the penalty is worked out if you break early, portability if you might sell and buy during the term, and whether the mortgage is registered as a standard or collateral charge.